Understanding Pakistan Customs: The Complete Guide for Importers
International trade appears simple until a shipment reaches Customs.
A buyer in Pakistan purchases goods from a supplier in China. The supplier produces an invoice. The cargo is collected, packed and transported to an airport or seaport. An airline or shipping line carries it to Pakistan. At that point, however, the commercial transaction enters an entirely different legal and regulatory environment.
The invoice price alone does not determine what Customs will accept. The cargo must be classified. Its customs value must be determined. Applicable duties and taxes must be established. Regulatory requirements must be satisfied. A declaration must be filed. Depending on the risk profile and nature of the consignment, documents may be scrutinised, cargo may be scanned or physically examined, and Customs may question classification, quantity, description or value.
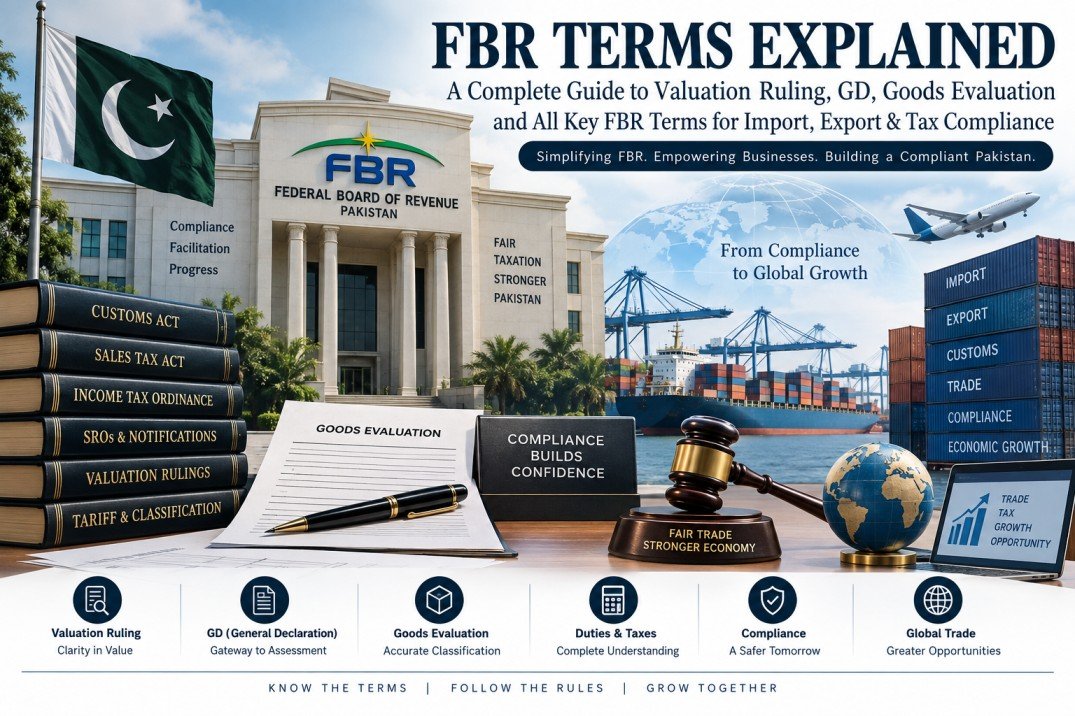
For this reason, anyone importing commercial goods into Pakistan should understand terms such as Goods Declaration (GD), Single Declaration (SD), HS Code, PCT Code, customs value, transaction value, Valuation Ruling, assessable value, Customs Duty, Additional Customs Duty, Regulatory Duty, Sales Tax, advance income tax, SRO, WeBOC, PSW, examination and assessment.
These expressions are not interchangeable. Each represents a different part of the customs-clearance system.
Pakistan Customs operates primarily under the Customs Act, 1969, Customs Rules, Pakistan Customs Tariff and connected tax and trade legislation. FBR’s current repository lists the Customs Act as amended up to 30 June 2026 and a Pakistan Customs Tariff for FY 2026–27.
Understanding these rules before importing can prevent one of the most expensive mistakes in international trade: calculating profit on the supplier’s price while ignoring the customs consequences of classification, valuation and taxation.
1. What Is FBR and What Is Pakistan Customs?
The Federal Board of Revenue (FBR) is Pakistan’s federal revenue authority. Pakistan Customs operates within this federal revenue structure and performs functions extending well beyond simply collecting duty.
According to FBR, Pakistan Customs is responsible for facilitating legitimate imports and exports, regulating trade, controlling contraband and collecting revenue.
For an importer, this means Customs effectively asks several fundamental questions:
What exactly are you importing?
Under which tariff classification does it fall?
What is its customs value?
What duties and taxes apply?
Does another government authority regulate the product?
Do the goods actually correspond with what has been declared?
The entire clearance process revolves around answering these questions correctly.
2. Goods Declaration — What Does GD Mean in Pakistan?
One of the most important customs terms is GD, meaning Goods Declaration.
A Goods Declaration is the formal customs declaration containing information about a shipment and the goods being imported or exported.
It is not merely an invoice.
It is the declaration through which information relevant to Customs processing is presented electronically. Depending upon the transaction, information may include the importer, supplier, transport details, invoice information, packages, weights, commodity description, classification, value, financial information and supporting documents.
The GD becomes one of the central records through which Pakistan Customs assesses an import or export consignment.
Historically, Pakistani traders became familiar with filing GDs through WeBOC, Pakistan Customs’ computerized clearance system.
FBR describes WeBOC as a web-based customs-clearance platform providing automated processing for import and export goods. Its modules include Goods Declaration, warehousing and other customs functions.
A very important misconception should therefore be eliminated:
The commercial invoice and the GD are not the same document.
The supplier issues the commercial invoice. The importer or authorized customs agent files the customs declaration using information and supporting evidence relating to the shipment.
3. What Is SD — Single Declaration?
Pakistan’s trade-digitalization system has introduced another important term: SD, or Single Declaration.
Pakistan Single Window describes a Single Declaration as the electronic submission of information for the clearance of import, export and transit-related goods through a single point.
The objective is to prevent traders from repeatedly submitting the same information separately to Customs and multiple government agencies.
This is especially important where imported products require action from another government agency.
For example, depending on the goods, regulatory involvement may come from an agency responsible for standards, health, agriculture, pharmaceuticals, security controls or some other regulated sector.
Instead of operating through disconnected paper-based processes, PSW is designed to route relevant information to participating agencies electronically.
4. GD vs SD: What Is the Difference?
Importers frequently use GD and SD as if they mean exactly the same thing. That is becoming increasingly inaccurate.
Pakistan Single Window currently explains that WeBOC remains the core Customs Management System, while PSW provides the broader trade interface.
PSW also states that where regulatory requirements are involved, filing through the Single Declaration system is mandatory. Where no such regulatory requirement applies, the trader may use the applicable WeBOC or PSW interface.
In practical terms, therefore:
A GD refers to the customs goods declaration traditionally associated with Customs/WeBOC processing.
An SD represents the broader Single Declaration mechanism within Pakistan Single Window, particularly valuable when Customs clearance interacts with other regulatory agencies.
The underlying purpose remains similar: accurately declaring a shipment for lawful clearance.
5. What Is WeBOC?
WeBOC stands for Web Based One Customs.
It is Pakistan Customs’ computerized customs-clearance system.
FBR describes WeBOC as an end-to-end automated system for customs clearance. Among its important functions are electronic declaration filing, electronic payments, customs processing, communication with traders and customs agents, and risk-based processing.
Many importers therefore use expressions such as:
“GD filed in WeBOC.”
“GD is under assessment.”
“GD has gone into examination.”
“Customs raised an objection.”
“GD has been out-of-charged.”
These expressions describe different stages of customs processing rather than completely separate systems.
6. What Is Pakistan Single Window — PSW?
Pakistan Single Window (PSW) is the wider electronic environment created to simplify cross-border regulatory procedures.
Rather than making an importer separately approach numerous government agencies, PSW aims to provide a single electronic entry point through which standardized trade information can be submitted and routed.
PSW explains that it supports electronic submission of information for import, export and transit clearance and integrates various regulatory processes.
This matters enormously for the future of Pakistan’s import system.
The difference can be understood simply:
WeBOC is fundamentally a Customs Management System.
PSW is the wider national trade and regulatory single-window ecosystem into which customs processes are integrated.
7. What Is an HS Code?
Every serious importer must understand the HS Code.
HS means Harmonized System.
The Harmonized System is an international method of classifying traded goods. Instead of identifying products only through ordinary commercial names such as “speaker,” “machine,” “LED light,” “shoe,” or “motor,” customs administrations use tariff classifications.
Pakistan Customs applies HS-based classification through the Pakistan Customs Tariff, or PCT.
FBR states that Pakistan Customs uses HS/PCT codes for classification and that Pakistan’s PCT codes consist of eight digits.
Classification is critical because the applicable PCT code can influence:
customs duty,
additional customs duty,
regulatory duty,
sales tax treatment,
income-tax treatment,
concessions,
exemptions,
regulatory permissions,
and whether a particular SRO applies.
A wrong HS/PCT code can therefore destroy an otherwise accurate import-cost calculation.
8. What Is a PCT Code?
PCT means Pakistan Customs Tariff.
The PCT code is Pakistan’s tariff classification used for imported and exported goods.
It is based upon the Harmonized System but applies Pakistan’s tariff structure at the national level.
For an importer, classification should never be treated as a guessing exercise.
Two products that appear commercially similar can fall under different classifications because of their composition, principal function, technical specifications, intended use or construction.
This is why an importer should establish the correct PCT classification before finalizing a large commercial shipment.
A supplier’s Chinese HS code can help describe a product, but it does not automatically determine Pakistan’s final customs classification.
Pakistan Customs ultimately applies Pakistan’s tariff nomenclature.
9. What Is Customs Valuation?
Classification answers:
What is the product?
Valuation answers:
What amount should Customs use as the value for assessing applicable duties and taxes?
This distinction is fundamental.
Pakistan’s statutory concept of customs value is governed principally by Section 25 of the Customs Act, 1969.
FBR’s published Section 25 states that the starting method is the transaction value—the price actually paid or payable for goods sold for export to Pakistan—subject to the conditions and adjustments prescribed by law.
The invoice therefore matters greatly.
But an invoice is not an unquestionable command to Customs.
Customs has statutory authority to examine whether a declared value is truthful and acceptable.
10. What Is Transaction Value?
Transaction value is the first and most important valuation concept.
In simplified terms, it starts with the price actually paid or payable to the foreign seller for goods sold for export to Pakistan.
However, legally required adjustments may have to be added where they are not already included.
Section 25 identifies items including transport to the port, airport or place of importation, loading and handling associated with that transport, insurance and certain other costs. It also addresses commissions other than qualifying buying commissions, containers, packing, assists, royalties and certain proceeds accruing to the seller.
Therefore, an importer cannot simply say:
“My Chinese supplier charged me USD 5,000, therefore Customs must calculate everything on USD 5,000.”
The legal question is whether USD 5,000, after the required adjustments and considering the circumstances of the transaction, represents an acceptable transaction value under Section 25.
11. FOB, CFR and CIF — Why Importers Should Understand Them
International suppliers commonly quote prices using Incoterms or similar commercial delivery expressions.
FOB — Free on Board generally represents a price up to the agreed export point, after which the buyer bears principal international freight and related costs under the relevant commercial arrangement.
CFR — Cost and Freight generally includes the goods and freight to the agreed destination but not the same insurance obligation found in CIF.
CIF — Cost, Insurance and Freight generally includes the goods, freight and insurance to the specified destination under that commercial term.
These expressions matter because Customs needs to know which costs are already incorporated into the declared commercial price and which statutory adjustments remain to be made.
Pakistan’s Section 25 specifically requires relevant transport, handling and insurance costs to the port, airport or place of importation to be considered where they are not already included.
The phrase “CIF value” is often used casually in trade, but importers should not substitute casual terminology for the actual statutory valuation calculation applicable to their shipment.
12. Customs Valuation Methods in Pakistan
An extremely important principle is that Customs valuation is not supposed to be arbitrary.
Where an acceptable transaction value cannot be established, Section 25 provides additional valuation methodologies.
The framework moves through concepts including the transaction value of identical goods, transaction value of similar goods, the deductive-value method, the computed-value method, and ultimately a fallback method based on the statutory valuation principles applied flexibly where necessary.
This structure reflects international customs-valuation principles.
The law also distinguishes between “identical” and “similar” goods. Identical goods are essentially goods matching in relevant characteristics, whereas similar goods need not be identical in every respect but should possess comparable characteristics and components enabling similar functions and commercial interchangeability.
This matters when Customs compares an importer with previous imports.
A comparison should have a legally relevant basis. It should not merely be:
“Someone once imported something with a similar name at a higher price.”
13. What Is a Valuation Ruling?
This is among the most misunderstood concepts in Pakistan’s import trade.
A Valuation Ruling, commonly called a VR, is a determination of customs value for specified goods or categories of goods under Section 25A of the Customs Act, 1969.
The Directorate General of Customs Valuation issues valuation rulings where the circumstances justify predetermined customs values for specified commodities.
FBR itself emphasizes an important point: Section 25A valuation rulings are intended to address circumstances where normal Section 25 assessments are problematic. FBR’s Valuation Directorate states that Section 25A should not simply override the normal Section 25 valuation framework for all goods.
That distinction matters.
A valuation ruling is not the same thing as Pakistan’s entire customs-valuation system.
Rather, it is a specific customs-value determination applicable to the goods and circumstances covered by that ruling until it is revised or rescinded by the competent authority. Section 25A expressly provides for such determinations.
14. Why Does FBR Issue Valuation Rulings?
Valuation disputes often arise in products where invoice prices vary significantly or Customs identifies persistent undervaluation problems.
The Directorate General of Customs Valuation may begin a valuation exercise following information from trade associations, importers, domestic manufacturers, FBR field formations, Customs Intelligence, clearance Collectorates, Post Clearance Audit or other relevant sources.
Stakeholder meetings may be conducted and import data, documents and market information may be examined before a ruling is finalized.
The purpose is to establish a defensible customs value using the valuation methods available under law, rather than simply inventing a price.
Recent FBR schedules continue to show valuation determinations, re-determinations and revision petitions being processed under Sections 25A and 25D in 2026, demonstrating that valuation rulings remain an active part of Pakistan’s customs system.
15. Declared Value vs Customs Value
This distinction alone can save an importer from a serious budgeting mistake.
Declared value is the value presented by the importer in the customs declaration based on the commercial transaction and supporting documentation.
Customs value is the value legally accepted or determined for customs purposes.
They may be equal.
But they do not have to be equal.
Suppose an importer purchases goods for USD 1.00 per unit. Customs may accept that transaction value if it satisfies Section 25.
However, if Customs has valid reasons to doubt the truth or accuracy of the declaration, further information may be required. Customs Rules provide that where reasonable doubts remain regarding the truth or accuracy of declared value, the transaction value may not be accepted as the customs value. The importer must be given an opportunity to provide relevant information.
This is why documentation matters.
An importer with a genuine price but weak evidence may create unnecessary difficulty for himself.
16. Can an Importer Challenge a Valuation Ruling?
Yes. There is a statutory mechanism.
Under Section 25D, where customs value has been determined under Section 25A, a revision petition may be filed before the Director-General of Customs Valuation within thirty days from the date of determination.
This is an important correction to another common misconception.
A valuation ruling is not merely an informal internal price list that an importer must silently accept without any legal remedy.
There is a prescribed statutory framework for revision.
Anyone considering litigation, revision or a formal customs dispute should, however, obtain advice from a licensed customs or legal professional on the exact facts and current law.
17. What Is Valuation Advice?
A Valuation Advice should also be distinguished from a Valuation Ruling.
FBR’s Directorate General of Customs Valuation states that it issues Valuation Rulings under Section 25A and Valuation Advices in transactions being processed under the provisional-determination framework of Section 81 by clearance Collectorates.
Therefore, whenever a trader hears the expression “valuation,” he should ask:
Is this ordinary Section 25 valuation?
Is there a Section 25A Valuation Ruling?
Is there a valuation advice?
Is the consignment under provisional determination?
Those are legally different situations.
18. What Is Customs Assessment?
Assessment is not the same thing as valuation.
Valuation determines the customs value.
Classification determines the tariff identity of the product.
Assessment brings the relevant information together to determine the customs liability and whether the declaration is correct.
Customs officers may review the declared classification, value, quantity, exemption claims, SRO claims, supporting documents and taxes before the declaration is finally processed.
This is why one can have a perfectly genuine invoice but still face an assessment issue involving classification or an exemption.
Likewise, one can have the correct PCT code but face a valuation dispute.
19. Assessment vs Examination
These two expressions are also routinely confused.
Assessment is fundamentally the customs determination concerning the declaration and liabilities.
Examination involves inspecting the goods themselves, physically or through applicable customs-control procedures, to verify whether the cargo corresponds with the declaration.
Customs may verify matters such as:
product description, quantity, weight, model, brand, composition, specification, origin, condition or other characteristics relevant to classification and valuation.
Pakistan’s computerized customs environment applies a Risk Management System. FBR describes WeBOC as operating Green, Yellow and Red processing channels, with different levels of intervention based upon risk.
A physical examination does not automatically mean that the importer committed an offence. It can simply represent a customs-control step.
20. What Is the Green Channel?
A shipment assigned to a Green pathway is generally processed with minimal customs intervention, subject to the applicable risk-management rules.
FBR material concerning risk-based processing describes Green declarations as capable of being cleared without scanning or examination in the circumstances covered by the relevant procedure.
Being placed in Green does not remove the importer’s legal responsibility for making a correct declaration.
Customs can retain audit, enforcement and post-clearance powers even where a shipment passes through a facilitated route.
21. What Are Yellow and Red Channels?
A Yellow pathway generally involves documentary scrutiny without the same level of physical intervention associated with a higher-risk consignment.
A Red pathway indicates greater customs intervention and may involve examination or other verification based on risk.
FBR’s description of WeBOC identifies Green as an immediate/no-intervention pathway, Yellow as document-based processing and Red as the higher-risk category.
An importer should therefore never promise customers:
“My cargo will always go Green.”
Risk selection belongs to the Customs system, not the freight forwarder.
22. What Is Provisional Assessment or Provisional Determination?
Sometimes Customs cannot immediately finalize liability because further testing, valuation inquiry or other information is needed.
Section 81 provides a mechanism for provisional determination of liability in qualifying cases.
The purpose is to allow customs processing while the final determination remains pending, subject to applicable legal safeguards relating to the potential duty/tax difference.
This concept is particularly relevant where goods require testing or additional inquiry.
It should not be confused with a normal completed assessment.
23. What Does “Out of Charge” Mean?
When customs processing has been satisfactorily completed and the required duties, taxes and formalities have been dealt with, the declaration may reach out-of-charge status.
In practical trade language, this is one of the most important moments in the clearance process because Customs has authorized movement toward release/delivery in accordance with the applicable system.
FBR procedures expressly use the term “out-of-charge” for completed GD processing and onward authorization to terminal operators.
However, Customs clearance and physical delivery are not always literally the same event.
Terminal, airline, shipping-line, handling, storage or logistics formalities may still need to be completed.
24. What Is Customs Duty — CD?
Customs Duty (CD) is the basic customs duty imposed under the tariff structure on applicable imports.
Its rate depends principally on the relevant PCT classification and any applicable exemption, concession or special regime.
Pakistan’s Customs Tariff for FY 2026–27 is currently published by FBR.
Therefore there is no responsible answer to the question:
“What is Pakistan’s customs duty?”
without knowing what product is being imported.
The correct question is:
What is the applicable customs duty for this specific PCT code under the current tariff and any applicable SRO or concession?
25. What Is Additional Customs Duty — ACD?
Additional Customs Duty (ACD) is an additional customs levy imposed on specified imports under the applicable legal framework.
It is separate from ordinary Customs Duty.
The FY 2026–27 budget introduced significant rationalization of ACD, including reductions and elimination for various tariff lines. FBR currently lists SRO 1063(I)/2026 as the operative 2026 notification relating to Additional Customs Duty.
This is precisely why relying on an old YouTube customs calculator or a three-year-old blog can produce the wrong landed cost.
26. What Is Regulatory Duty — RD?
Regulatory Duty (RD) is another import levy applied to specified goods.
It serves tariff and trade-policy purposes and is separate from ordinary Customs Duty.
For FY 2026–27, FBR reports substantial rationalization of the RD regime, and its active import SRO repository currently lists SRO 1064(I)/2026 for Regulatory Duty.
Not every product attracts RD.
The applicable PCT code and current notification must be checked.
27. What Is Sales Tax on Imports?
Imported goods can also attract Sales Tax under Pakistan’s Sales Tax Act, subject to applicable exemptions and special provisions.
FBR explains that goods imported into Pakistan are subject to sales tax unless specifically exempted under the law, including exemptions provided through the Sixth Schedule or applicable notifications.
The current Sales Tax Act published by FBR is available in a version amended through 30 June 2026.
Again, an importer should not automatically apply a remembered historical rate to every product.
The exact tax treatment should be checked for the particular commodity and current fiscal year.
28. What Is Import-Stage Income Tax?
Pakistan also collects advance income tax at the import stage under Section 148 of the Income Tax Ordinance, subject to the applicable category, rate, exemption or treatment.
The Supreme Court has described Section 148 as providing for collection of advance tax on imports and notes that it is collected in the same procedural setting as customs duty.
For costing purposes, this means an importer must not think only in terms of “customs duty.”
An import may potentially involve several different fiscal components.
29. What Is FED?
FED means Federal Excise Duty.
FED does not apply identically to every imported product, but it can form part of the import-tax structure where the relevant goods fall within the applicable federal-excise regime.
Accordingly, a complete landed-cost calculation may need to consider FED in addition to Customs Duty, ACD, RD, Sales Tax and import-stage Income Tax where those levies legally apply.
30. Why There Is No Universal “Pakistan Import Tax Percentage”
This point deserves emphasis.
There is no legitimate universal statement such as:
“Pakistan import duty is 20%.”
or
“Customs takes 35%.”
or
“Air cargo tax is 15%.”
Those statements are commercially dangerous.
The final fiscal treatment depends on variables including:
PCT classification × customs value × applicable tariff rate × ACD × RD × Sales Tax × import-stage Income Tax × FED where applicable × exemptions/concessions/SROs × origin/preferential treatment × importer-specific circumstances.
Even the 2026–27 federal budget changed CD, ACD and RD treatment across numerous tariff lines.
Therefore, a serious freight company should quote customs-related charges only after identifying the actual commodity and relevant regulatory treatment.
31. What Is an SRO?
SRO means Statutory Regulatory Order.
SROs are legally important notifications through which the government/FBR can implement exemptions, concessions, additional duties, regulatory duties, procedures and other measures under statutory authority.
An SRO can radically change the effective tax treatment of a product.
For example, FBR’s current active import-SRO repository includes separate 2026 notifications for Additional Customs Duty and Regulatory Duty, along with preferential-trade measures and other customs notifications.
Therefore, checking only the basic tariff rate can still produce the wrong answer.
The customs professional must check whether any relevant SRO modifies the normal treatment.
32. What Is the Fifth Schedule?
The Fifth Schedule to the Customs Act contains important concessionary and exemption-related customs-duty provisions for specified goods and circumstances.
FBR publishes an updated Fifth Schedule alongside the annual Pakistan Customs Tariff. The current customs-tariff repository includes the Fifth Schedule updated for FY 2026–27.
A product showing one general rate in the tariff may therefore qualify for a different effective rate where the conditions of a concession are lawfully satisfied.
The conditions matter just as much as the rate.
33. What Is an FTA or PTA Concession?
Pakistan has trade arrangements under which qualifying goods originating from certain partner countries may receive preferential customs treatment.
However, merely purchasing goods from a particular country does not automatically create preferential origin.
Rules of origin and documentary conditions generally have to be satisfied.
A Certificate of Origin can therefore become crucial where preferential tariff treatment is claimed.
Importers should distinguish:
country of shipment, country of purchase and country of origin.
They are not always identical.
34. What Is Certificate of Origin?
A Certificate of Origin (COO) is a document evidencing the origin of goods.
Origin can affect tariffs, preferential-treatment claims, trade restrictions and regulatory treatment.
For some normal imports, origin information may be straightforward.
For preferential treatment under a trade agreement, however, the prescribed origin documentation and rules must be satisfied.
Pakistan Single Window also supports electronic trade-related certification processes, including electronic Certificates of Origin through relevant government integration.
35. What Is IGM?
IGM means Import General Manifest.
Before individual consignments can be processed, the carrier’s manifest information identifies cargo arriving in Pakistan.
For air cargo, the airline or its handling chain transmits relevant manifest information.
For sea cargo, the shipping line performs the corresponding function.
A GD does not exist in isolation: Customs must be able to associate the declared shipment with the arriving cargo/manifest information.
Errors in consignee name, airway bill, manifest particulars or shipment data can therefore delay clearance.
36. What Is an AWB?
AWB means Air Waybill.
It is a primary air-cargo transport document containing shipment and carriage information.
In consolidated freight, traders may encounter:
MAWB — Master Air Waybill
and
HAWB — House Air Waybill.
The Master Air Waybill generally relates to the airline/master consolidation, while a House Air Waybill identifies an individual shipment within the consolidation arrangement.
For China-to-Pakistan air cargo, correct AWB and manifest information is essential because Customs needs to identify the cargo arriving against the import declaration.
37. Commercial Invoice
The Commercial Invoice is one of the most important documents in customs valuation.
It should truthfully describe the commercial transaction.
Depending on the goods and transaction, relevant information commonly includes supplier and buyer details, product description, quantity, unit price, total price, currency, delivery terms and invoice date.
A vague invoice saying merely “accessories” or “parts” may create difficulties if the real shipment contains multiple identifiable commercial items.
Customs classification depends upon what the goods actually are—not whatever vague description happens to be convenient.
38. Packing List
The Packing List explains how the goods are physically packed.
It can contain package count, contents, gross weight, net weight, carton details and other shipment information.
During examination, Customs may compare physical goods against declared information and the packing list.
A packing list should therefore not be treated as meaningless paperwork.
It helps connect the commercial transaction with the physical cargo.
39. Gross Weight, Net Weight and Chargeable Weight
These three expressions should not be confused.
Gross Weight includes the goods together with relevant packaging.
Net Weight generally reflects the weight of the goods themselves without the relevant outer packaging.
Chargeable Weight is primarily an air-freight commercial concept used by airlines and freight forwarders for determining freight charges.
Air cargo may be charged on actual weight or volumetric weight depending upon the applicable airline/freight formula.
That does not mean “chargeable weight” automatically becomes the legal customs value.
Freight charges can affect customs valuation because transport to the place of importation is relevant under Section 25, but freight-billing weight and customs value are fundamentally different concepts.
40. What Is Customs Examination?
Customs examination means inspection of the goods to verify that the shipment corresponds with what has been declared.
Customs may verify quantity, weight, description, model, specifications or other identifying characteristics.
Where discrepancies are discovered, the matter can move beyond ordinary clearance and lead to amendment, reassessment or enforcement proceedings depending upon the circumstances.
FBR customs procedures provide examples where differences between declared information and physically examined goods may be sent to the Appraising Officer for further legal action.
Therefore, deliberate misdescription is not a legitimate “cost-saving technique.”
It creates customs risk.
41. What Is Misdeclaration?
Misdeclaration generally refers to materially incorrect information supplied to Customs concerning a consignment.
Depending upon the circumstances, misdeclaration may involve matters such as:
description, value, quantity, classification, origin, brand, model, weight or regulatory status.
Not every typo automatically becomes customs fraud.
But intentional or material false declarations can create serious consequences under customs law.
Professional import planning should focus on correct classification and documentation—not clever wording designed to disguise the shipment.
42. What Is Undervaluation?
Undervaluation occurs when goods are declared at an artificially reduced value in order to reduce customs liability.
This is exactly one of the risks Pakistan’s valuation system is designed to address.
FBR’s Directorate General of Customs Valuation expressly states that part of its role is dealing with circumstances involving widespread undervaluation while maintaining a lawful valuation process.
There is an important difference between:
genuinely negotiating an unusually low purchase price
and
creating a false invoice showing a price lower than what was actually paid.
The first may be commercially legitimate and capable of proof.
The second can constitute customs misconduct.
43. What Documents Can Support a Genuine Low Transaction Value?
Where Customs questions an unusually low price, the importer should be able to demonstrate the commercial reality of the transaction.
Useful evidence can include genuine commercial invoices, purchase contracts, payment records, bank or financial documentation, supplier correspondence, price lists, purchase orders, proforma invoices, evidence of quantity discounts, evidence of clearance or distressed stock, and comparable supplier quotations where relevant.
The Customs Rules recognize the importer’s right to provide further information when transaction value cannot immediately be accepted.
Good documentation turns “trust me, this is the actual price” into evidence.
44. What Is a Financial Instrument in PSW?
Pakistan Single Window has integrated customs declarations with banking and trade-payment information.
Historically traders used Electronic Import Form (EIF) and Electronic Form-E (EFE) processes.
PSW states that these older consignment-wise forms are being replaced through electronic trader/banking-profile and Financial Instrument integration between PSW and authorized banks.
The Financial Instrument therefore forms part of the electronic trade-payment ecosystem and can be associated with declarations subject to the applicable PSW and banking requirements.
45. What Are LPCOs?
LPCO generally refers to Licences, Permits, Certificates and Other documents/authorizations required from government agencies.
Not every commodity can be imported merely by paying duty.
Some products are regulated because of health, safety, agriculture, standards, pharmaceuticals, environmental, security or other policy considerations.
PSW was designed in significant part to integrate these regulatory permissions into one electronic environment.
This is why product compliance should be checked before the cargo leaves China.
Discovering after arrival that a permit was required can turn a profitable shipment into a storage-cost nightmare.
46. What Is an NOC?
NOC means No Objection Certificate.
Depending on the commodity, a relevant government body may require or issue an NOC or another permit/certificate before customs release.
The exact authority depends entirely on the product.
An importer therefore should never ask only:
“What is the customs duty?”
The better pre-import question is:
Is this item freely importable, restricted, regulated or subject to an LPCO/NOC requirement?
47. What Is RMS?
RMS means Risk Management System.
Instead of physically examining every single shipment, Customs uses risk-based controls to determine the appropriate degree of intervention.
FBR expressly identifies risk-management processing as a feature of WeBOC.
Risk may be influenced by many factors within Customs systems and enforcement policy.
Importers should therefore maintain consistent, accurate and defensible declarations.
Trying to “game” the system may create far larger risks than the duty allegedly saved.
48. What Is Post Clearance Audit — PCA?
Customs clearance does not always mean customs scrutiny has ended forever.
Post Clearance Audit (PCA) allows Customs to examine commercial records and declarations after goods have been released.
Section 25 itself preserves Customs’ authority concerning verification of declarations, documents, records and values, and FBR’s Valuation Directorate identifies Post Clearance Audit among the field formations capable of referring valuation matters.
Consequently, import documentation should be preserved properly even after cargo leaves the airport or port.
49. What Is AEO — Authorized Economic Operator?
In customs terminology, AEO means Authorized Economic Operator.
It should not be confused with “Answer Engine Optimization” in digital marketing.
Pakistan’s AEO framework is designed around identifying reliable and compliant economic operators and providing trade-facilitation benefits.
FBR states that the legal basis for Pakistan’s AEO programme was introduced through Section 212A of the Customs Act, with rules issued subsequently under the program.
The broader idea is simple:
Businesses demonstrating strong compliance and supply-chain controls can qualify for enhanced facilitation under the applicable framework.
50. The Complete China-to-Pakistan Import Clearance Journey
For an importer purchasing commercial goods in China, the overall process can be understood as one connected chain.
First, the buyer identifies the exact product rather than relying on a vague commercial name. The product should be checked for its likely PCT classification, importability, applicable regulations, valuation rulings and expected tax structure.
The supplier then prepares genuine commercial documentation. Cargo is packed and handed over to the freight operator. For air cargo, an Air Waybill is created and relevant transport/manifest information moves through the airline handling chain.
Before or during customs filing, the importer or customs agent prepares the appropriate GD/SD and associates the shipment with the necessary commercial, financial and regulatory information.
Customs then processes the declaration through the computerized system.
The goods are classified under the applicable PCT code.
The customs value is determined under Section 25 or, where applicable, in accordance with an in-field Valuation Ruling or another legally applicable valuation mechanism.
Applicable Customs Duty, ACD, RD, Sales Tax, import-stage income tax, FED or other lawful charges are determined according to the commodity and current fiscal framework.
The Risk Management System determines the required level of intervention.
Documents may be reviewed.
The shipment may be scanned.
Cargo may be physically examined.
Queries can be raised.
Where Customs is satisfied and applicable payments and requirements are completed, the GD/SD proceeds toward clearance and out-of-charge.
The airline, terminal, custodian or logistics provider then completes the physical release process, after which the cargo can move toward the consignee’s destination.
This is why professional air freight is far more than putting cartons on an aircraft.
It is the coordination of commercial documentation, transportation, classification, valuation, taxation, customs compliance and physical delivery.
51. Why Importers Lose Money Even When Freight Is Cheap
Many first-time importers obsess over one number:
freight per kilogram.
That is a serious mistake.
A supplier may offer a low product price.
A freight forwarder may offer a cheap air-freight rate.
Neither guarantees that the shipment will be profitable.
The real commercial calculation is closer to:
Purchase Cost + China Inland Logistics + International Freight + Insurance where applicable + Customs Duties/Taxes + Regulatory Costs + Customs Clearance + Airport/Terminal Costs + Local Delivery + Financing Cost + Risk Margin = True Landed Cost
Classification and valuation can often affect the final economics more heavily than saving a small amount on freight.
A professional importer therefore calculates the customs position before purchasing—not after the goods arrive in Pakistan.
52. Valuation Ruling Example in Practical Terms
Assume an importer purchases a product from China for USD 4 per unit.
He should not immediately conclude:
“My duty will be calculated on USD 4.”
First, the PCT classification must be established.
Next, the importer should determine whether an applicable Valuation Ruling exists.
If no special ruling controls the case, the normal Section 25 valuation framework must be considered.
If the declared transaction value is acceptable and all required statutory adjustments have been included, it may form the customs value.
If Customs reasonably questions the declared value, supporting information may be requested.
If a valid Section 25A Valuation Ruling covers the relevant goods and circumstances, that ruling becomes highly significant for customs assessment.
Only after the customs value and classification are established can the fiscal consequences be calculated properly.
This is the correct sequence.
Doing the calculation backwards is how importers get surprised.
53. Frequently Asked Questions About FBR Customs and Imports
What is GD in Pakistan Customs?
GD means Goods Declaration. It is the customs declaration through which details of imported or exported goods are submitted for Customs processing.
What is SD in Pakistan Customs?
SD means Single Declaration. It is the Pakistan Single Window mechanism through which standardized information for import, export and transit clearance can be electronically submitted through a single interface.
What is a Valuation Ruling?
A Valuation Ruling is a customs-value determination issued under Section 25A of the Customs Act for specified goods or categories of goods.
What is PCT code?
PCT means Pakistan Customs Tariff. Pakistan Customs uses eight-digit PCT/HS-based codes for tariff classification.
Does Customs always accept the supplier invoice?
No. Transaction value is the primary valuation method, but Customs may investigate the truth or accuracy of a declared value and request supporting information where reasonable doubts exist.
Is valuation the same as assessment?
No. Valuation determines the customs value. Classification identifies the tariff heading. Assessment determines customs liability based on the declaration and applicable law.
Does every shipment undergo physical examination?
No. Pakistan Customs uses a Risk Management System and different processing channels. Some shipments may clear with little intervention while others undergo documentary review, scanning or examination.
What is customs assessable value?
In practical trade usage, assessable/customs value refers to the value on which applicable import duties and taxes are determined under the relevant statutory rules. It should not automatically be equated with the supplier’s invoice total.
What is SRO?
An SRO is a Statutory Regulatory Order. Customs-related SROs can prescribe or alter exemptions, concessions, additional customs duty, regulatory duty and other import conditions.
What is ACD?
ACD means Additional Customs Duty.
What is RD?
RD means Regulatory Duty.
What is CD?
CD means Customs Duty.
What is PSW?
PSW means Pakistan Single Window, Pakistan’s electronic single-window system for cross-border trade and regulatory processing.
What is WeBOC?
WeBOC means Web Based One Customs, Pakistan Customs’ computerized customs-management and clearance system.
What does out-of-charge mean?
It means Customs processing has reached the stage where the declaration is authorized for release/delivery under the applicable customs system, although terminal or logistics formalities may still remain.
How can I check the latest import duty in Pakistan?
Determine the correct PCT code first, then consult FBR’s current Pakistan Customs Tariff, Fifth Schedule and active SROs. For FY 2026–27, FBR has published the applicable tariff and updated customs notifications.
Can a Valuation Ruling be challenged?
Yes. Section 25D provides for a revision petition before the Director-General of Customs Valuation within thirty days from determination under Section 25A.
54. The Most Important Rule for Pakistani Importers
The most dangerous sentence in importing is:
“Last time somebody imported it at this rate.”
That information may be useful, but it is not enough.
The other importer may have used a different PCT classification.
The product may have been different.
Its country of origin may have been different.
A new Valuation Ruling may have been issued.
An old ruling may have been rescinded.
An SRO may have changed.
ACD or RD may have changed after the federal budget.
A concession may have expired.
The other importer may have been eligible for a relief you are not entitled to claim.
The declared value may have been accepted in one transaction and questioned in another.
Customs law evolves continuously.
Indeed, FBR’s FY 2026–27 changes substantially rationalized a range of CD, ACD and RD rates, proving why historical landed-cost calculations cannot safely be reused indefinitely.
55. Conclusion: Customs Knowledge Is Part of Importing, Not an Afterthought
Successful importing is not merely about finding inexpensive products in China.
It is about understanding the entire chain between the supplier’s factory and the buyer’s warehouse in Pakistan.
A professional importer knows that product classification determines the tariff identity of the goods; valuation determines the customs value; assessment determines the legal customs liability; examination verifies the physical cargo; GD/SD communicates the shipment to Customs; and PSW/WeBOC provide the electronic infrastructure through which much of that process operates.
Valuation Rulings, SROs, the Fifth Schedule, PCT classification, ACD, RD, Sales Tax, advance income tax, permits and regulatory approvals can materially affect the landed cost of an import.
Ignoring these concepts before shipping is not simplification.
It is gambling.
For businesses importing from China to Pakistan, the safest commercial approach is therefore to identify the exact product, establish its likely PCT classification, check current FBR tariff treatment and Valuation Rulings, identify any regulatory permissions, calculate the realistic landed cost, and only then commit to a commercial shipment.
That turns importing from guesswork into a controlled business process.
MohsinAirCargo — China to Pakistan Air Cargo
MohsinAirCargo helps businesses coordinate cargo movement from China to Pakistan, including shipment planning, supplier-side coordination, consolidation, air freight and import logistics.
Before sending commercial cargo, importers should provide an accurate product description, quantity, weight, commercial value and supporting details so that the shipment can be assessed properly from a logistics and customs perspective.
Never undervalue, misdescribe or disguise commercial goods to reduce customs liability. A cheaper shipment is worthless if it creates a customs dispute, seizure risk, penalty or unexpected landed cost.
Regulatory Note
This guide is educational and reflects official FBR and Pakistan Single Window materials reviewed for Pakistan’s FY 2026–27 framework as of September 2026. Customs classifications, Valuation Rulings, SROs, duties, taxes, import-policy conditions and regulatory requirements can change. Product-specific customs treatment should therefore be verified against the latest FBR tariff, active SROs, applicable Valuation Rulings, PSW requirements and professional customs advice before importing.